By Alex Stark
The Bill Comes Due: A $40 Trillion Milestone, a Shrinking Diesel Pool, the Real Cost of Bad AI, and the End of the Efficiency Model
In my little corner of the supply chain, I’m still trying to get myself into fall mode. It just feels wrong to be seeing Halloween commercials when it’s not even Labor Day yet. Autumn is out there for sure. I woke up this morning to temperatures in the 50s. There are small pockets of leaves starting to lose their vibrant green color.
Here are four things that caught my attention this week, and they share an uncomfortable though-line. In each case, a cost deferred for years finally surfaced, and the thing that would normally have absorbed it was no longer there. Fiscal room, spent. Refining capacity, closed. Customer patience, exhausted. Supply chain slack, intentionally optimized away.
None of these fixes itself, either. That’s the part that may have implications in the logistics and supply chain space.
Let me know what you’re seeing.
1. The National Debt Passed $40 Trillion, and the Interest Is the Real Story
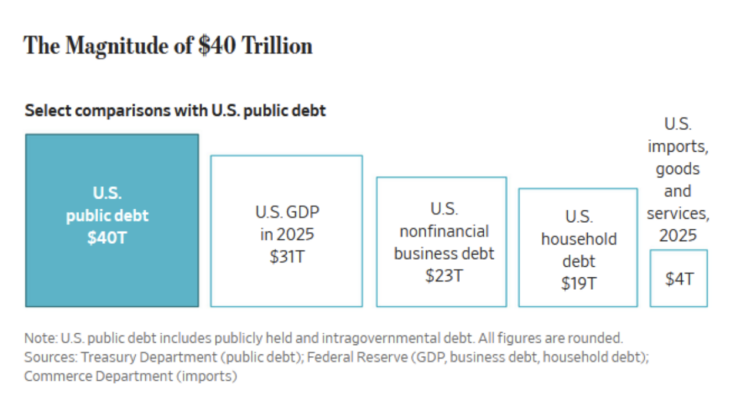
The U.S. Treasury released data Wednesday showing gross national debt at $40.05 trillion, crossing the threshold months earlier than forecasters expected. It has doubled since 2017 and quadrupled in under twenty years. At the start of this century, it sat at $5.7 trillion, and the country was running a surplus.
The headline number gets the attention, certainly. It’s massive. The interest line is the one that actually changes things. Annual interest payments now top $1 trillion, making interest the government’s second-largest expense behind Social Security and roughly equal to Medicare. Those costs have more than tripled in five years. The deficit for the first ten months of this fiscal year is $1.8 trillion.
How It Got Here
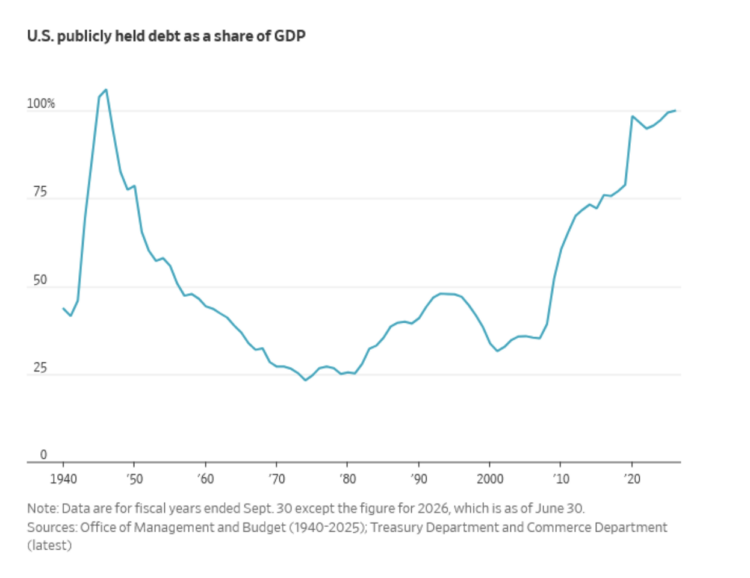
The Peterson Foundation, the nonpartisan, nonprofit organization that focuses on America’s fiscal and economic challenges, attributes the trajectory to four factors: repeated rounds of tax cuts, spending growth, crisis response, and the structural growth of entitlements and interest costs. Borrowing accelerated under both parties, and pandemic response accounts for roughly a third of the debt added since 2017. The U.S. debt-to-GDP ratio is expected to keep rising. Looking ahead, the Congressional Budget Office projects debt will rise to 120% by 2036, surpassing the post-World War II record of 106%.
Why This Lands on Your Desk
Heavier Treasury issuance puts upward pressure on yields regardless of what the Fed does with the short-term rate. Last week, I wrote that July CPI cooled enough to drop September hike odds to 42%. Current odds for the September meeting are now around 30%, with a 70% probability of a hold. Equipment financing, facility debt, and AI investments are all affected by the rates. Probably best to think prudently about 2027 budgets.
2. Diesel Buyers Are Competing for a Pool That Keeps Shrinking
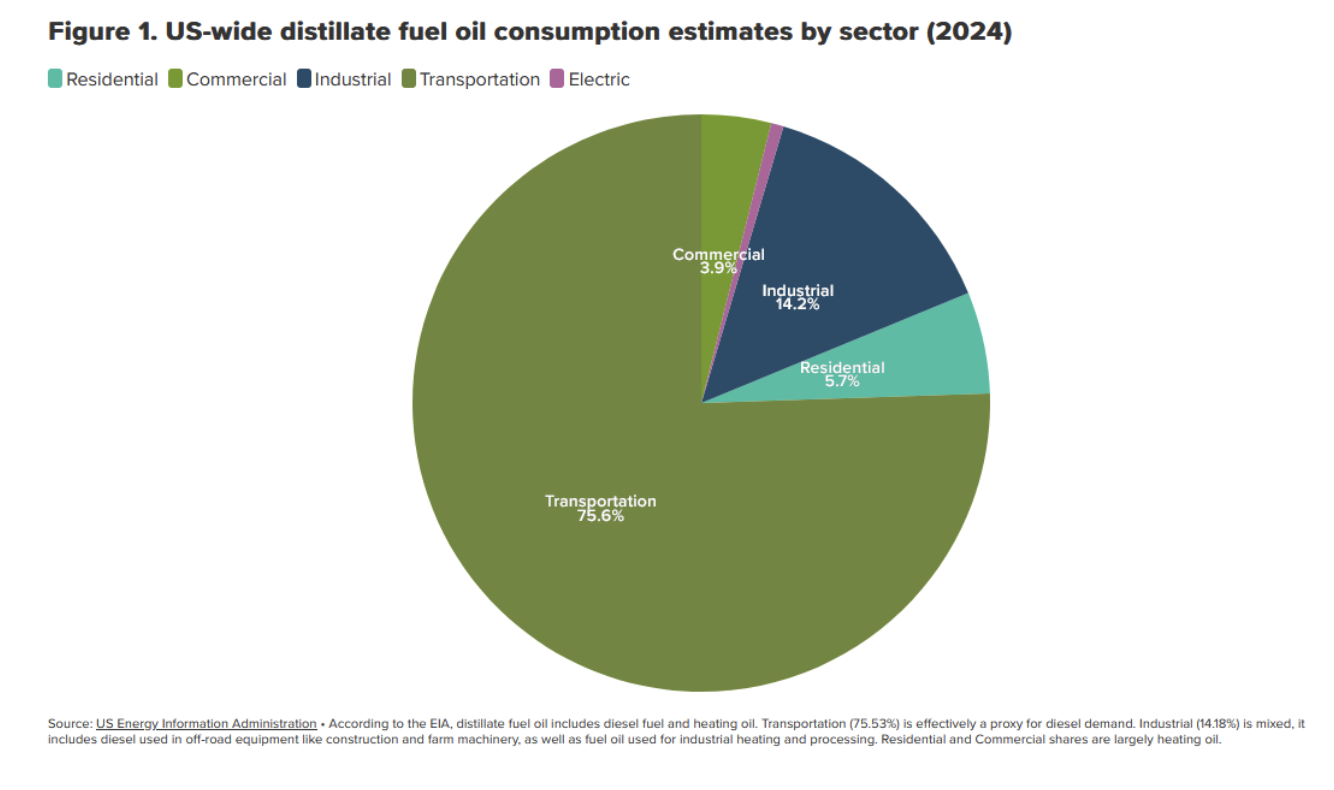
U.S. distillate inventories, which include diesel and heating oil, stood at roughly 107 million barrels in early August, the lowest level at this point in the year since 1996. That’s the U.S. Energy Information Administration’s data, not a forecast. Goldman Sachs put diesel at the epicenter of a broader fuel squeeze, and buyers are now competing for a smaller pool of product.
Four Things Pressing at Once
- Structural refinery closures. Roughly 1.2 to 1.3 million barrels per day of U.S. crude processing capacity has been retired or converted since 2019. This includes LyondellBasell’s Houston refinery, Phillips 66 in Wilmington, and Valero’s Benicia plant. These are filings and shuttered units, not projections.
- Russia, the world’s second-largest diesel exporter, has extended its export ban as its refineries remain under sustained drone attacks.
- Hormuz and the Iran war continue to disrupt Gulf product exports. Global refinery throughput in July was about 5 million barrels per day below the previous year.
- China has tightened its fuel export quotas.
The timing is the uncomfortable part. Late summer and fall is harvest time across the nation, when farms burn enormous volumes of diesel. It’s also when the country is supposed to be building heating oil stocks for winter. Both draw land on an inventory already sitting at a thirty-year seasonal low.
Here’s the itch that keeps scratching me. This is not a price spike. It doesn’t appear to be something that will just snap back. Refining capacity does not return because prices went up. It’s the same structure as the driver shortage, which is a regulatory reset rather than a wage problem, and the freight recovery, which is supply-driven rather than demand-driven. When supply is structurally smaller, waiting for normal isn’t a strategy. We’ve passed that exit.
For shippers, fuel surcharge exposure deserves a real look before Q4 rather than during it. If you’ve been treating diesel volatility as a line item that averages out over a year, this may be the year it doesn’t.
3. Three Numbers on What Bad AI Actually Costs You
I came across a CX Dive piece I couldn’t put down when I read it earlier this summer. I kept it in one of my files when I knew it would work into the 4 Things. It’s mainly because I cannot look away from all things AI. The article pulls together three figures putting a price on AI failure, and it’s pretty compelling.
- 91%. The accuracy of Google’s AI model, per an analysis by the startup Oumi for the New York Times. Google handles more than five trillion searches a year, so 91% accuracy means billions of wrong answers annually. Ninety-one percent sounds excellent right up until you do the math.
- Three in five. Consumers who will repeat themselves exactly once to an automated system before abandoning it entirely, according to a Parloa study. One repeat.
- More than a third. Consumers who report feeling immediately frustrated the moment they learn support is AI-powered, per a Kim.cc survey of 1,000 U.S. consumers. Frustrated before the interaction even begins.
Kim.cc CEO Sachin Jaiswal made the observation that nails this issue:
Customers do not see bad AI support as a tech issue. They see it as a company problem.”
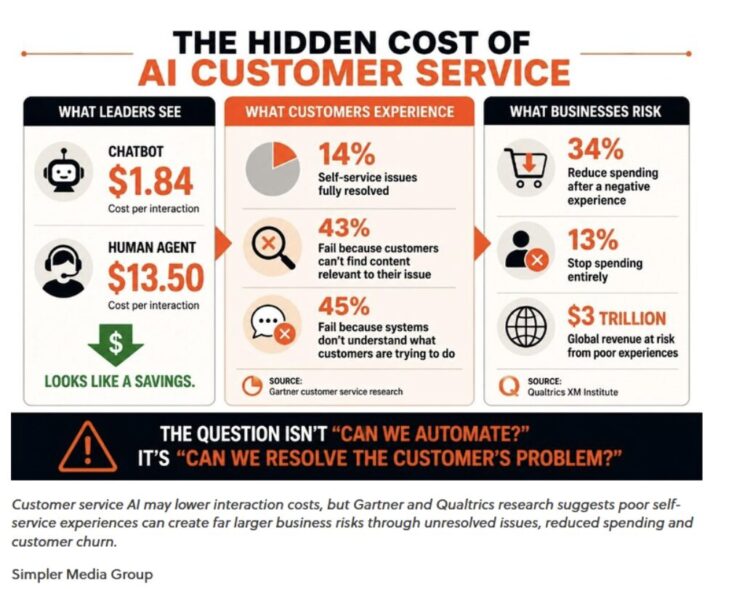
A company problem. The damage isn’t one bad ticket. It’s trust, then reputation, then the customer. It’s worth noting that Forrester predicted at the end of last year that in 2026 a third of companies would actively harm their customer experience through premature AI self-service, driven specifically by pressure to cut costs.
This is the cost side of the Gartner finding I wrote about two weeks ago, in which two-thirds of supply chain digital investment goes to AI, while 55% of chief supply chain officers can’t say what it returns. It’s also why Target pairing its AI hire with a UX promotion last week was the right instinct. And it’s the friction piece from July in harder numbers. The question then was whether a given piece of friction serves the customer or the business. AI deployed to cut costs rather than to serve customers is friction that serves the business, and customers can tell the difference immediately.
If you’re putting AI in front of customers, the metric isn’t deflection rate. It’s whether the customer got what they needed. Those are different numbers, and they can move in opposite directions while the dashboard still looks green.
4. The Great Supply Chain Reset, and Why the Efficiency Model Ran Out
A piece published this week in SupplyChainBrain by Stephen Williams lays out the argument as straightforward as I’ve seen it.
For decades, supply chains were designed around the simple principle of efficiency.”
Manufacturing concentrated in low-cost regions. Inventory centralized. Logistics networks optimized to move product from the factory floor to the doorstep as cheaply as possible. Globalization rewarded scale, consolidation, and specialization, and the companies that squeezed out the most cost savings won.
And here’s what resonated, which the piece gets 100% correct. That model worked. It delivered extraordinary growth and made e-commerce possible at a scale we now take completely for granted. This isn’t an argument that the last thirty years were a mistake. It’s an argument that the assumptions underlying the model no longer hold, and that the design that produced the growth is the same design that produces the fragility. We need to build our supply chains for a different future.
Accurately Capturing the Trend
The articles this week are a function of the same iteration. The efficiency logic that closed marginal refineries is the same logic that centralized inventory and replaced a service rep with a chatbot. Each decision was locally rational. Each one removed slack from the system.
Slack is what absorbs shock, and it never appears as a line item until the moment you need it and discover it’s gone.
This is the thesis of what I’ve been circling since May, when the theme was what we built for the easy years, and in June, when it was that nobody is waiting for normal anymore. That piece originated from the same firm with the argument I covered in May about AI relocating bottlenecks rather than eliminating them.
Resilience costs money in the good years and pays in the bad ones, which is precisely why it keeps getting cut. The practical version is simply knowing which parts of your network have slack and which don’t and being deliberate about it rather than surprised by it. That’s a fair description of the work we do.
When the Bill Comes Due
Decades of deficits, and now interest is the government’s second-largest expense. Years of refinery closures, and now inventories sit at a thirty-year seasonal low heading into harvest and winter. Cost-cutting through bots and AI, and now a third of customers are frustrated before they even type a word. On top of all that, we’ve spent thirty years optimizing for efficiency, resulting in a system with nothing left to absorb a shock.
None of these items reverse on their own. Debt doesn’t shrink without making tough decisions. Refineries don’t reopen because prices rose. Customer trust doesn’t magically rebuild itself just because the quarter ended. The supply chain doesn’t grow slack without careful deliberation. Every one of these items requires someone to choose to fix it, and each one gets more expensive the longer it takes.
The good news/bad news situation. The bad news is the impact of this on our industry. The good news is their collective visibility. We have the knowledge of the issue and can commit to alternate solutions.
Bonus #1: Every State’s Economy, Matched to a Country
I’m a map guy. I’ve loved geography since I was a kid. I had a great-uncle, former U.S. Navy, who would routinely quiz me about capitals, both states and countries, and general knowledge of locations around the globe. So, when I saw this infographic, I was in heaven. It pairs every U.S. state with a country of comparable GDP.
California, Texas, New York, and Florida have economies large enough that they would qualify as G-20-sized countries on their own.
Bonus #2: The Most Fun States
Apparently, my computer is now serving me exactly what pushes my buttons. More maps! Somewhere, my beloved great-uncle is smiling. This time it’s the “most fun” states in the U.S. I’ll admit I secretly love it whenever Pennsylvania, my home state, ranks higher in any poll, any ranking, or even history in general, than Ohio.
Bonus #3: Every State’s Favorite Soda
Forget it, I’m rolling, so please indulge me. Maybe I went 0-for-2 on the first two links. I hope not. If you’re still with me after all this, I’m thankful for your readership and your patience. This map shows each state’s favorite soda. I’m not a soda drinker, but I do like a crisp ginger ale with lots of ice every once in a while.
Again… PA. Winner. No contest against Ohio.
You’re welcome.
One Last Thing… Lake Mead and the Hoover Dam
One more thing before we go, on a serious note. News about the water levels in the West is front and center this hot summer, and it’s genuinely shocking to see Lake Mead’s level shrinking. It got me researching how the Hoover Dam was constructed. Still simply amazing, almost 100 years later, and there are really cool black-and-white photographs in this story.
It also happens to be somewhat connected to the industry news in this post. A reserve drawn down faster than it refills, where the trouble only becomes visible once the waterline drops far enough for everyone to see it.
Praying for rain for you all out there. Nice, steady rain (no downpours), with an extra dose of snow for all the mountains this winter.
Remember, it costs nothing to be kind.